Payday-Proof Money Plan: Budget, Save, Invest, Crush Debt
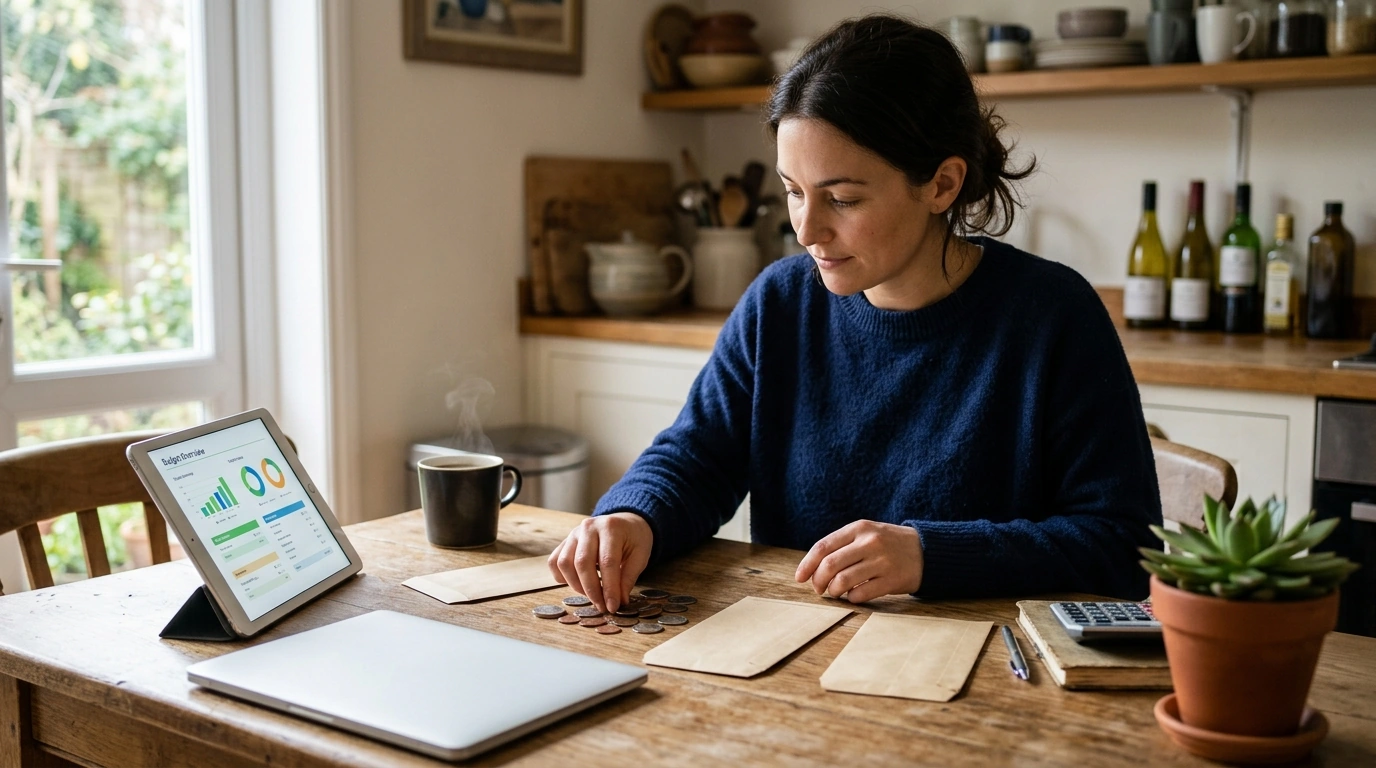
Personal Finance Made Easy: a clear path through budgeting, saving, investing, and debt
Money gets complicated fast when every decision competes for the same paycheck. Our Personal Finance Made Easy Ebook – Budgeting, Saving, Investing & Debt Management Guide for Financial Freedom is built for real life: you set up a budget you’ll actually use, build savings without feeling deprived, start investing with confidence, and manage debt with a plan that doesn’t rely on willpower alone. Use it as a step-by-step guide for building financial freedom one practical choice at a time.
If you like learning with straightforward checklists and repeatable routines, our team designed this ebook to help you move from “I know what I should do” to “I did it this week.” (And while we can’t offer personal financial advice, we can give you a simple system you can adapt to your situation.)
Who this ebook fits best
- Anyone who wants one simple system that covers budgeting, saving, investing, and debt management together (not as separate disconnected “projects”).
- People tired of tracking every penny and ready for a structure that still allows flexibility.
- Beginners who want plain-language explanations and a repeatable routine for paydays and monthly check-ins.
- Busy households that need clarity: what to pay first, what to automate, and what to ignore until later.
The money map: set priorities before you set numbers
Before you calculate a single percentage, you need a “money map”—a quick set of priorities so your budget reflects the life it’s funding. Instead of pretending every month is identical, you define what must be protected first (essentials), what keeps you stable (buffers and savings), what moves you forward (goals), and what makes life enjoyable (flex).
When your map is clear, daily decisions get easier: if a purchase doesn’t fit the map, you delay it, swap it, or reduce it—without spiraling.
A simple 4-bucket money flow (customize to your life)
| Bucket | Purpose | Examples | How to run it |
|---|---|---|---|
| Essentials | Keep life running | Rent/mortgage, groceries, utilities, transportation | Fund first; keep predictable with bill dates and reminders |
| Stability | Prevent setbacks | Starter emergency fund, insurance, sinking funds | Automate a set amount each payday (even small) |
| Goals | Build the future | Extra debt payments, investing, education, big purchases | Pick a priority order and focus on one main goal at a time |
| Flex | Enjoy without guilt | Dining out, hobbies, gifts, fun money | Set a cap; when it’s used, pause or choose a cheaper option |
Budgeting that holds up on real paydays
One of the quickest ways to break a budget is building it around a neat calendar month while your income hits on different days than your bills. Our team recommends a payday-based flow: each paycheck gets assigned jobs (bills due before the next check, groceries, a savings transfer, and a realistic flex cap).
- Start with a baseline budget for a “typical” month, then add a quick adjustment routine for irregular costs like car repairs and annual subscriptions.
- Add guardrails instead of perfection: caps for flexible categories and a buffer line for the unexpected.
- Do a weekly 10-minute check-in: confirm upcoming bills, review remaining “Flex,” and choose one small correction for the next week.
Saving without waiting for a “better month”
Saving gets easier when you stop treating it like whatever is left over. A starter emergency fund (even a modest one) reduces stress and helps prevent small surprises from becoming new debt.
- Automate transfers timed to payday so saving happens before spending decisions begin.
- Create sinking funds for predictable “surprises” (holidays, back-to-school, car maintenance, birthdays) to smooth out the year.
- Increase in small steps: raise the automated amount after each pay raise, paid-off bill, or payoff milestone.
For additional budgeting tools and plain-language guidance, the Consumer Financial Protection Bureau (CFPB) budgeting resources are a helpful companion to the routines you’ll build here.
Debt management that’s firm but realistic
Debt payoff works best when the plan can survive real life. That means stabilizing first (keeping essentials current and building a small buffer), then paying minimums on everything while focusing extra money on one balance at a time.
Investing: start simple and protect the habit
If you want a trusted overview of investing fundamentals, SEC Investor.gov’s introduction to investing is a solid, beginner-friendly reference.
A 30-day routine that turns “knowing” into “doing”
Helpful digital guides from our store
- Personal Finance Made Easy Ebook – Budgeting, Saving, Investing & Debt Management Guide for Financial Freedom
- Memory Boost Worksheets for Students & Adults | Printable Digital Download (great if you want structured worksheets and quick daily practice habits)
- Must-Know Pet First-Aid Cheat Sheet | Emergency Printable Guide for Pet Owners (a practical add-on for emergency readiness alongside your financial buffer)
FAQ
Is this ebook suitable for beginners who feel behind on money basics?
Yes. We wrote it in plain language with a step-by-step structure that starts with priorities, then builds a simple budget and small automations before moving into more advanced decisions like investing.
Does the approach work if income or expenses change month to month?
Yes. You’ll use paydays as your planning anchor, keep a baseline budget for “normal” months, and rely on quick adjustments, buffers, and sinking funds so variable months don’t force you to restart from scratch.
What should come first: saving, paying off debt, or investing?
A practical sequence is: keep essentials current, build a starter emergency fund, make minimum debt payments, focus extra money on one payoff goal, and automate investing once your cash flow is stable. The right pace can vary by situation, but the structure stays consistent.

Leave a comment